Horsebox Insurance
Protect your motorised horse lorry with an annual policy
95% of reviewers recommend Harry Hall*
93% agree One Club Membership is good value for money*

87% of One Club Members have been with us for years*

No premium hikes if you claim

Enjoy exclusive member perks and legal support

Trusted British brand since 1891
You pay the same price everybody else pays, no hidden pricing

Experienced, Friendly Yorkshire Customer Service Team
Every year we donate thousands of pounds to equine charities
From 3.5-tonne horseboxes to large HGVs
Harry Hall’s competitive and comprehensive horsebox insurance can cover a wide range of horsebox sizes and configurations, from smaller 3.5 tonne horseboxes to larger 7.5 tonne trucks with living quarters, and beyond. Covering up to £100,000 as standard.
As an added optional extra; recovery, delivery and hire costs can be added to your policy to ensure you and your horse get home safe. Plus, extensions for alternative travel and reward are available.
Why get horsebox insurance?
Horsebox insurance helps protect your vehicle against financial risks like theft, accidental damage and fire, whether you’re travelling with horses or parked up. As horseboxes or horse lorries are a motorised vehicle it is also a legal requirement to have insurance in place before driving on UK roads.
At Harry Hall, you could cover from third party to comprehensive with options like lost keys, broken windscreens and medical expenses all potentially added to your cover.
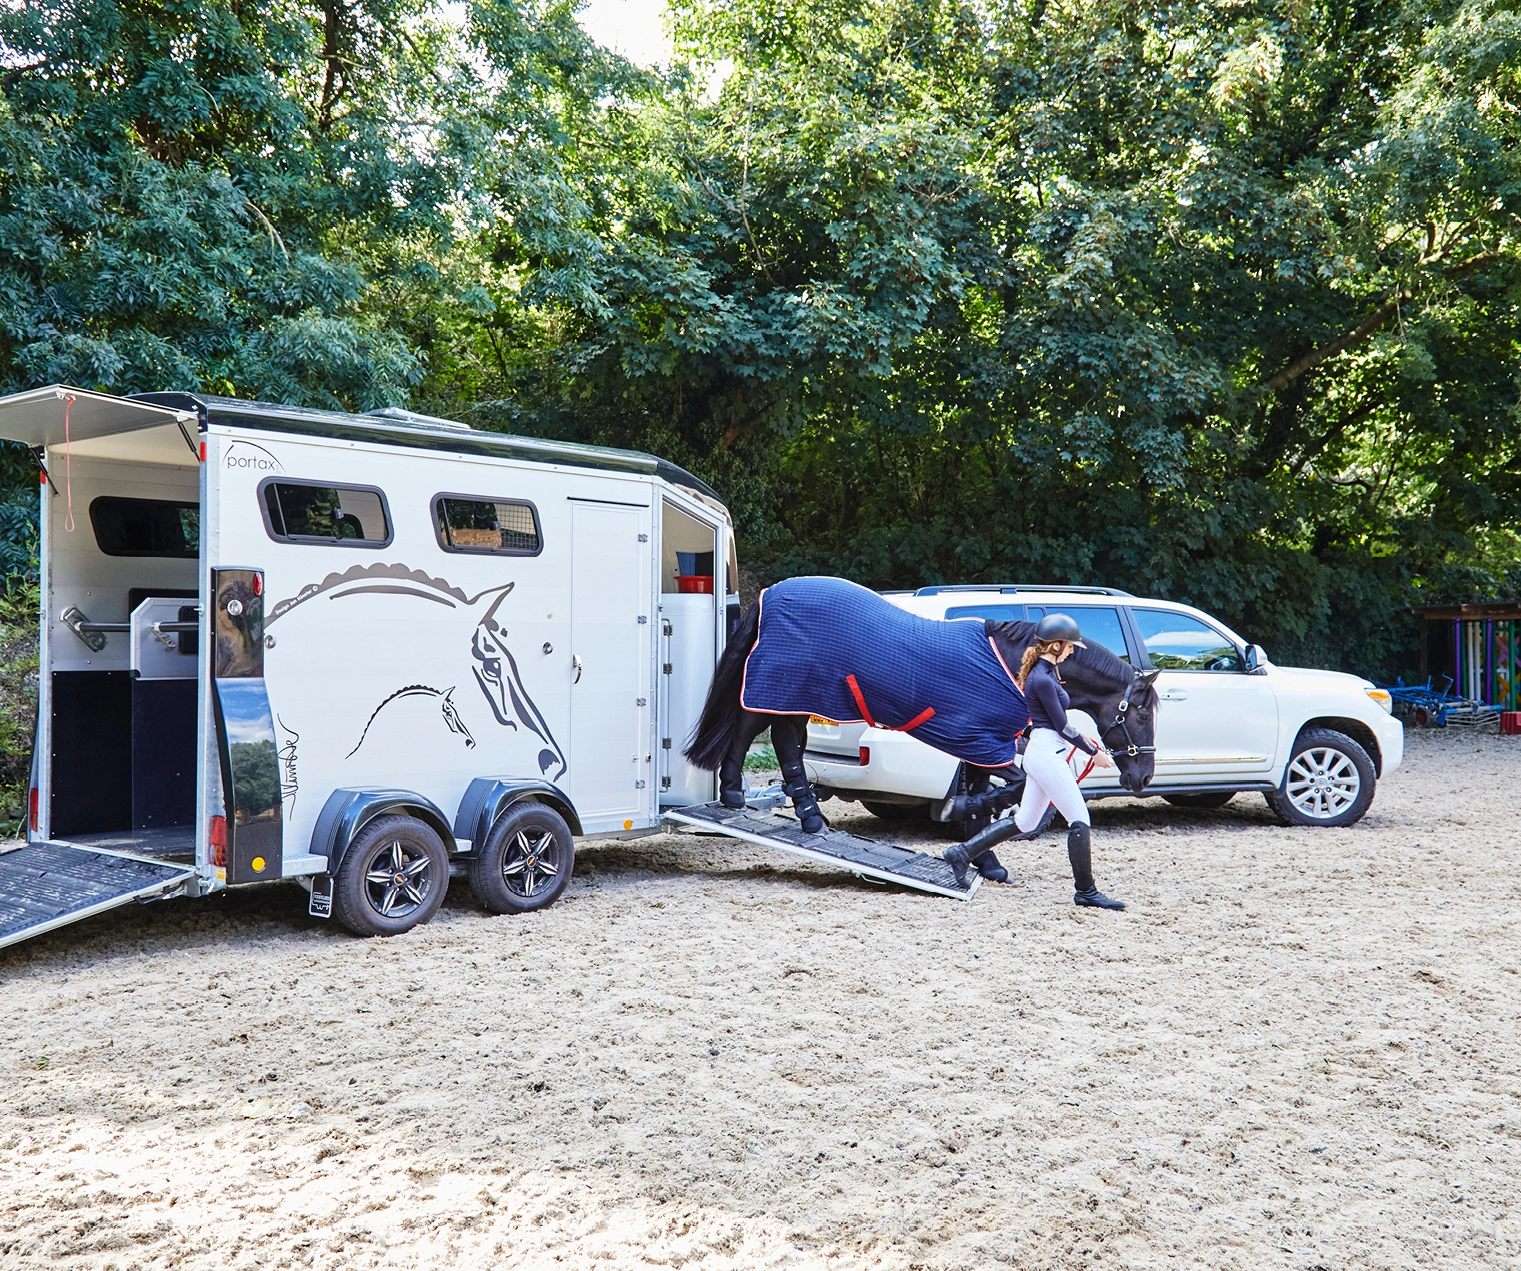
Understand your horsebox insurance options
Third party liability cover protects you if your horsebox causes damage to someone else’s property or injures someone while being used or towed.
All amounts you may legally have to pay as a result of an accident while you are driving or using your vehicle:
- Death or bodily injury (Unlimited)
- Damage to property caused vehicle (£5m)
- Prosecution defence costs (£2m)
- Additional Legal services (Included as standard)
- Uninsured loss recovery (£100k)
This coverage protects you if your horsebox causes damage to someone else’s property or injures someone while being used or towed.
As noted above in third party cover plus:
- Vehicle loss or damage caused by fire, lightning, self ignition, explosion, theft, or attempted theft (Market value)
- Personal effects (£250)
This covers damage to your horsebox resulting from accidents, fire, theft, vandalism, or other covered perils.
As noted above in third party and fire and theft cover plus:
- Accidental damage to the vehicle (Amounts stated are per event unless stated otherwise)
- New vehicle replacement (Market value)
- Windscreen/ glass cover (Unlimited)
- Audio, visual and navigational equipment (£1k)
- Loss of keys/ replacement locks (£1,250)
- Personal accident
- Death (£10k)
- Loss of sight (£10k)
- Loss of limb (£10k)
- Emergency accommodation and travel expenses (£100 per person; £400 any one incident)
- Medical expenses (£500 per person)
- Child car seat (£500 per incident)
- Personal belongings (£500 per vehicle)
Policy is provided by Peliwica Ltd
Horsebox Breakdown Cover – In Partnership with ERS
Keep calm when the unexpected happens — whether you’re on the road to a competition or just heading home with your horse, ERS Equine Breakdown Insurance has your back.
- Assistance at the roadside if your towing vehicle or horse box breaks down
- 24/7 emergency call-out service
- Nationwide support across the UK and recovery to nearest repairer
- Full recovery of your vehicle, horse trailer, and horses to a UK destination of your choice (roadside rescue)
- Assistance at your home address
- Help with vehicle hire, public transport or overnight accommodation
Horsebox Insurance Explained
Horse lorry insurance is essentially a type of horsebox insurance, typically for larger, HGV-style vehicles. The key difference lies in the size and classification of the vehicle, but both are covered under the insurances arranged at Harry Hall.
Yes. Both 3.5T and 7.5T horseboxes are classed as motorised vehicles and require insurance that covers road use and third-party liability.
Harry Hall offers policies tailored to these common horsebox sizes and other configurations, ensuring your vehicle and horses are protected on the road.
Whilst a standard horsebox policy doesn’t include breakdown cover it can easily be added online at Harry Hall.
As trailers aren’t motorised, they get their own version of insurance that covers costs related to theft or damage. You can arrange a policy online at Harry Hall for your trailer too.
No, the policies available are for horsebox owners and not for short term horsebox hire.
The horsebox insurance will cover the vehicle itself, and any fixed items listed within the policy schedule, but will not cover contents carried or left inside the vehicle.
Social, Domestic and Pleasure
This covers you if you’re transporting your own horses purely for personal reasons, shows, competitions or hacking out somewhere further afield. As long as no money changes hands, occasionally carrying a friend’s horse is usually still fine under this category too.
Business Use
If you use your horsebox in connection with your own equestrian business — for example, a professional rider or trainer transporting owners’ horses to shows without taking a fee for the transport itself — you’ll need Business Use rather than Social, Domestic and Pleasure. The distinction isn’t about whether you have a business, it’s about whether the horsebox is being used as part of it.
Hire and Reward
If you’re being paid to transport other people’s horses, offering self-drive hire or you profit from doing so, whether that’s horse transport as a service or competing and taking a cut of winnings, you’ll need Hire and Reward cover. This reflects the higher risk of carrying horses you don’t own, for a fee.
Getting this wrong can void a claim entirely, so if you’re not sure which category fits, our team can talk it through with you, call our friendly Yorkshire based customer service team on 01274 711011.
The weight of your horsebox affects your premium, and it determines which driving licence category you legally need. Here’s how the three common classes break down.
3.5 Tonne Horseboxes
A 3.5 tonne horsebox is the most common starting point for owners with one or two horses. If your horsebox has a maximum authorised mass (MAM) of 3,500kg or less when fully loaded — horses, tack, fuel, passengers, the lot — it can usually be driven on a standard Category B car licence. For more advice please seek advice from Driving licence categories – GOV.UK
Worth knowing: many 3.5t horseboxes with larger living quarters or heavier fit-outs can tip over this limit once loaded, even if the empty vehicle looks well within it. Always check the weight plate, not just the horsebox’s marketed size.
Harry Hall covers 44 tonnes horseboxes as standard, with cover up to £100,000.
7.5 Tonne Horseboxes
Horseboxes with a MAM between 3,500kg and 7,500kg — commonly sold as “7.5 tonne” — need a Category C1 licence to drive legally. If you passed your car test before 1 January 1997, you may already hold C1 entitlement without realising it (check the back of your licence). If you passed after that date, you’ll usually need to pass an additional C1 test.
7.5 tonne horseboxes suit owners regularly travelling with multiple horses or larger breeds, often with more generous living accommodation on board.
Harry Hall covers 7.5 tonne horseboxes, including those fitted out with living quarters.
HGV Horseboxes (Over 7.5 Tonnes)
Anything over 7,500kg MAM falls into full HGV territory and requires a Category C licence, the same licence used for large goods vehicles. This typically applies to bigger professional or competition horseboxes carrying several horses, extensive living quarters, or both.
Harry Hall’s horsebox insurance extends beyond 7.5 tonnes to cover these larger configurations too — call 01274 711011 for a tailored quote.
Not sure which weight class your horsebox falls into? Check the weight plate for your Maximum Authorised Mass (MAM) that figure, not the horsebox’s marketed size, is what determines the licence you need and the cover you should be arranging.For more advice please seek advice from Vehicle registration: Vehicle identification number – GOV.UK
We’re rated excellent and 4.74 out of 5 stars
Rachel says: “I’m a big Harry Hall fan, I’ve always found their products and customer service spot on! I’m a One Club member and also have trailer insurance. 10/10!”
Excellent based on 15,000 from

Policy summaries
Admin Fees
- All premiums quoted are inclusive of Insurance Premium (IPT) at the prevailing rate, and subject to a £35.00 administration fee.
- You may cancel this policy anytime during the period of insurance and we will refund the premium for the exact number of days left on the policy. Any underpayment by you will be offset against any cancellation return of premium
- Amendments to policies and copies of insurance schedules and certificates will be administered by Peliwica.
Full terms and conditions can be viewed here
Conditions and Exclusions
- In the event of a claim for loss of or damage to the insured vehicle or windscreen, a financial contribution for the first part of each claim is payable by you. Refer to your Insurance Policy Schedule for all payable excess contributions.
- Theft of your vehicle is excluded when the keys are left on or in it and it is not locked and secure.
- Cancellation Terms: You may cancel this policy within 14 days of purchase, or within 14 days from the day on which you receive the insurance documents whichever is the later. Where cover has not yet started we will provide a full refund of the premium paid. Alternatively if cover has started, we will refund the premium for the exact number of days left on the policy, as long as no claim has been made. We will also do this if you want to cancel your policy within 14 days after renewal. If you cancel outside the cooling off period, you may cancel this policy anytime during the period of insurance, and we will refund the premium for the exact number of days left on the policy. Any underpayment by you will be offset against any cancellation return of premium.
Full terms and conditions can be viewed here
Related products
Public Liability Cover
One Club Gold and Platinum members get £10M public liability and £10K personal accident as standard with the option of including up to £3,500 rider fracture cover.
Vet Fees Insurance
Multi-horse protection for accidental external injuries up to claim limits of £1,500, £3,000 or £6,000. With no upper age limit to worry about.
Horse Trailer Insurance
Be prepared for whatever the day brings with Harry Hall Trailer Insurance. Recovery, delivery and hire trailer costs included to ensure you and your horse get home safe.
Current customer?
Important Information
- Equario Insurance (Guernsey) Limited, is registered in Guernsey under Registration Number 69867 and is regulated by the Guernsey Financial Services Commission. Equario Insurance (Guernsey) Limited’s registered office is Level 5, Mill Court, La Charroterie, St Peter Port, Guernsey GY1 1EJ.
- Peliwica Ltd is registered in England no:10764297 and regulated by the Financial Conduct Authority (FCA) with firm reference number 808026.
- ERS Syndicate 218 at Lloyd’s is managed by IQUW Syndicate Management Limited –Registered in England and Wales No. 00426475. Authorised by the Prudential Regulation Authority and regulated by the Financial Conduct Authority and the Prudential Regulation Authority (FRN 204851).
- Commercial Express Quotes Limited is authorised and regulated by the Financial Conduct Authority. (FRN 311067). Company No. 03862468
- Harry Hall International Limited is authorised and regulated by the Financial Conduct Authority (FCA) our firm reference number is 968047. You may check this on the Financial Services Register by visiting the FCA website.
- Personalised products are excluded from the FREE UK delivery offered to Gold and Platinum Members on HarryHall.com. Free returns is offered to UK mainland customers only.
- The LawAssure platform and legal helpline is available to the following members: Purchased or renewed a Gold, Gold Family, Gold Plus, Gold Plus Family, Platinum or Platinum Family Membership after 1st February 2024 and over the age of 18. See full terms of service here.
- Harry Hall donates £0.10p from new, single orders to our nominated charity partners. Please note the following exclusions apply: renewals and gift cards
- Shopping vouchers are delivered to marketing consented customers by email or in the One Club app and have a limited expiration and specific terms of use. Please refer to the email or promotion terms for further details and note that vouchers are single use for active members only and have a minimum order value.
- In an effort to reduce paper and plastic usage, One Club membership has moved online! To view your policy documents please log in to the Harry Hall App or visit the My Account section of the website. You will also be emailed your policy documents and important phone numbers.